Overfitting in EA Backtests: When a Perfect Curve Hides Risk
Overfitting in EA backtests happens when an expert advisor is tuned too closely to historical noise instead of a repeatable market pattern. The result can be a very smooth equity curve, apparently strong profitability and low drawdown that fail on new data or live execution. An EA backtest should be treated as a hypothesis to stress-test with out-of-sample checks and parameter sensitivity, not as proof of future performance.
What is overfitting in backtesting, and why does it matter for EAs?
Overfitting in backtesting means the EA logic or parameters have been tuned too precisely to the same historical period used for evaluation. The more trials, filters and parameter combinations are tested, the easier it becomes to find a beautiful result that is partly random.
In practice, the risk is not only that a backtest is bad; the risk is that it looks too good. A curve with little volatility, unusually low drawdown or steady gains in nearly every month should be treated as a reason for deeper validation.
How MT5 EA optimization can create a fragile curve
The MetaTrader 5 Strategy Tester can run an EA many times with different parameter sets and then select the strongest combinations; that is useful for research, but without out-of-sample testing it can also create a result fitted too closely to the past. The official MetaTrader guide explains that optimization runs a strategy several times with different sets of parameters.
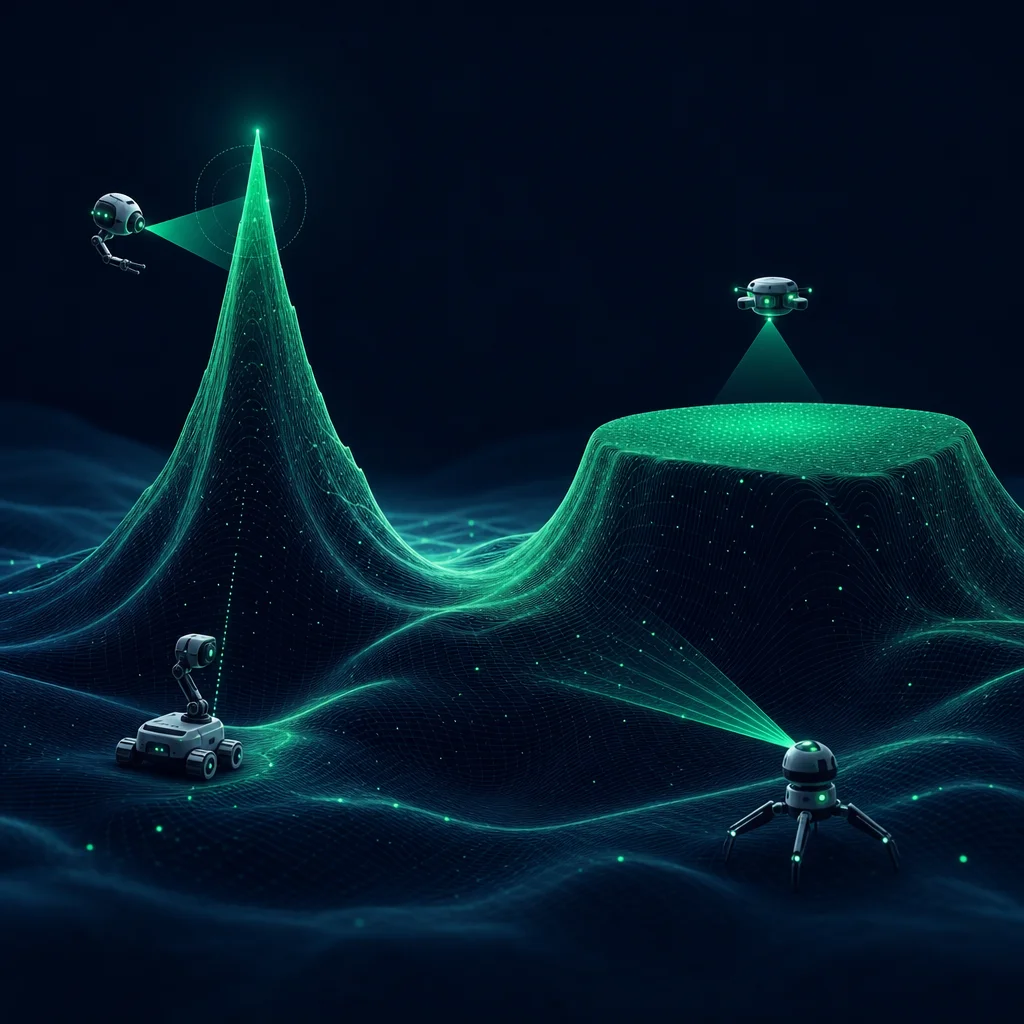
The issue becomes more serious when a user simply selects the “best pass.” An MQL5 article on the optimization surface explains that focusing on a single peak can be misleading, because a small change in parameters or market regime may quickly damage the result; the surrounding parameter surface matters, not only the final number in the best pass.
A practical checklist for spotting an overfit EA backtest
This checklist is written for MT5 EA users. Its purpose is not to accept or reject a system quickly, but to separate results worth investigating from results that look fragile.
- Split the test into in-sample and out-of-sample periods; choose parameters only on the first part and leave the second part untouched.
- If a small parameter change sharply alters profit, drawdown or trade count, treat the result as fragile.
- Model more realistic trading costs: spread, commission, slippage, swap and execution delay should be close to broker conditions.
- Do not read net profit alone; review drawdown, underwater periods, trade count, losing months and monthly profit/loss distribution together.
- If the result works only on one symbol, one timeframe or one short period, treat it as a hypothesis rather than sufficient evidence.
- Instead of choosing the prettiest curve, check whether nearby parameter ranges behave in a similar and acceptable way.
When the equity curve looks perfect, what risks remain hidden?
A smooth equity curve can be useful, but it does not prove system quality by itself. In an EA backtest, the key question is whether the smoothness comes from stable logic or from fitting the past too precisely.
| Backtest sign | Hidden risk | Control question |
|---|---|---|
| Very steady profit | Bad historical scenarios may have been filtered away | Does the out-of-sample period show a similar distribution? |
| Very low drawdown | Stop, filter or entry timing may be over-tuned | What happens under worse execution costs? |
| Best result at one parameter point | Random peak on the optimization surface | Do nearby parameters also produce acceptable results? |
| Low number of trades | Too much dependence on a few historical trades | If a few large trades are removed, is the result still defensible? |
| Large improvement after many filters | More model freedom and higher noise-fitting risk | Does every filter have a real economic or behavioral hypothesis? |
What do out-of-sample and walk-forward tests show?
An out-of-sample test checks how the EA behaves on data that was not used when selecting its parameters. Walk-forward testing repeats that idea across multiple time windows to see whether the system is fitted only to one historical segment.
A study of 888 trading algorithms found that common backtest metrics, including Sharpe ratio, had limited value in predicting out-of-sample performance, and that more backtesting was associated with a larger gap between in-sample and out-of-sample performance; that finding is consistent with the risk of overfitting in backtesting shown in this out-of-sample performance study.
How LFP reads a backtest as a statistical hypothesis
The transparent approach is to read a backtest not as a profit promise, but as a report of historical behavior. In that view, the equity curve, drawdown, trade count, markets traded and underwater periods are all parts of one risk picture.
For a multi-market EA, robustness does not come from one attractive chart alone; the question is whether the result remains explainable across markets, periods and realistic trading costs. That turns EA optimization into a risk-control process, not a search for the best-looking number.
Frequently asked
- Is a very good backtest always a sign of overfitting?
- No, but a very smooth or heavily optimized backtest deserves more scrutiny. Confidence improves only if the result remains stable in out-of-sample testing, worse execution assumptions and small parameter changes.
- What is the best way to reduce overfitting in an EA backtest?
- A combination of out-of-sample testing, walk-forward testing, parameter sensitivity analysis and more realistic execution costs is usually better than relying on one optimization metric. MT5 also offers a Forward option to verify optimization results on a later period.
- Is a high profit factor enough to trust an EA?
- No. Profit factor should be read together with drawdown, trade count, losing months, underwater periods and stability across markets.
- What is the difference between walk-forward testing and a normal backtest?
- A normal backtest usually evaluates one historical period; walk-forward testing selects parameters on one window and tests them on the next. Repeating that process reduces dependence on one specific historical segment.
- Is it a problem if an EA works well on only one symbol?
- Not necessarily, but concentration in one symbol can increase dependence on that market’s specific conditions. The system should still be reviewed across different periods of the same symbol and, where relevant, related markets.
This is educational material, not investment advice. All performance figures are backtest results, not live trading, and are no guarantee of future results.